The case for Gold

Gold, Infinite Debt, and the Problem of Capital Storage: Has The Hotelling Moment Arrived?

March 9, 2011 Gregor Macdonald

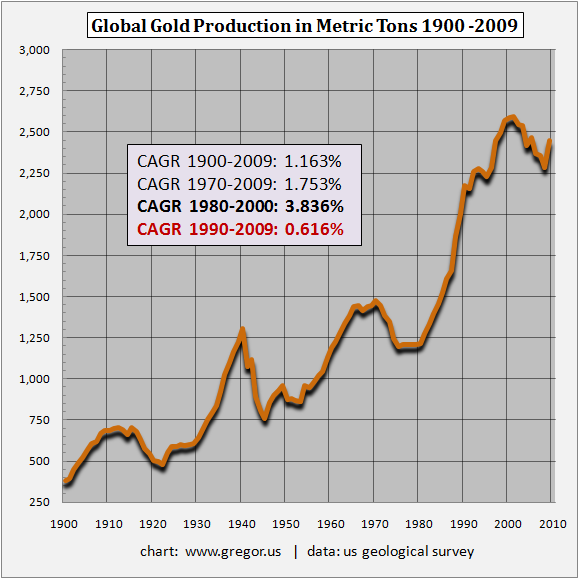
One of the reasons that gold retains its competitiveness as a capital-storage unit is the rather slow and plodding rate at which supply is brought to market. Since 1900, compound annual growth of world gold production comes in at 1.163%. That particular rate is below the growth rate for a number of other natural resources. But in particular: it’s well below the rate of credit production–the “resource” which now plagues the developed world. Indeed, the over-production of credit the past twenty-five years has once again driven capital back into hard assets such as gold. This brings up an intriguing subject: the conversion of resources into financial capital, and the conversion of financial capital back into resources. First, let’s take a look at a century of gold production. | see: World Gold Production in Metric Tons 1900 – 2009.


From 1980-2000 global gold production grew at a strong, compound annual growth rate (CAGR) of 3.836%. But that was after a very slow production rate for forty years, between 1940 and 1980. In the past decade global production of gold has not only slowed again but fallen steadily, with a notable uptick in 2009 as the decline temporarily reversed. Indeed, since the new millennium, the story of gold will be familiar to those who have watched oil: as prices steadily rose, supply growth fell.

The migration of capital, between the world of natural resources and the world of finance, has been addressed by any number of thinkers, one of the more compelling being Harold Hotelling. Writing in the Journal of Political Economy in 1931, Hotelling proposed that a rational producer of resources would only be inclined to extract and sell that resource if the investment opportunities available with the capital proceeds were greater than simply leaving that resource to appreciate in the ground. So, given Hotelling’s theory of resource extraction, what has happened to gold production since the year 2000? Does the chart reflect geological and cost limits to increasing gold production, even as the price rose from $250.00 to $1000.00 per ounce? Or, has there been some moderate yet gathering decision on the part of global gold producers to extract gold more slowly? After all, why extract gold to merely convert gold into paper currency, beyond the need to pay for the cost of production and provide, say, a dividend to shareholders? In other words, at the rate at which the price has been rising, why hurry to extract the gold?

These same questions have long been asked in the world of energy extraction as well. Why did global oil production advance so quickly into late 2003 as the oil price was rising towards the high 30′s, only to peak out for the past six years as price skyrocketed? We must assume that oil producers in the West, governed mostly by for-profit enterprises, were doing everything possible to lift production. The conclusion is rather easy: they couldn’t lift production, even with a doubling of price. But in contrast to BP, Shell, Exxon, Total, Chevron, and Conoco, what about the NOCs–the National Oil Companies? Is it possible they were inclined to apply some form of scarcity rent, holding back production slightly? Echoing statements made at least twice last decade, King Abdullah of Saudi Arabia repeated himself last Summer when he remarked about future Saudi oil production: “I told them that I have ordered a halt to all oil explorations so part of this wealth is left for our sons and successors God willing.” | see: Global Crude Oil Supply 2002 – 2010 in mbpd (updated through November 2010)

As lovely and reasonable a view offered by Hotelling in his The Economics of Exhaustible Resources, there is little evidence that oil producers are any more rational than individuals. The history of global oil production would appear to be governed more by geology, than any future projections of how to best invest oil revenues. North Sea oil was largely extracted in the cheap oil era, and peaked as oil prices began to take off earlier last decade. This was also true for Indonesia, and of course several decades before with the United States. Indeed, the bulk of world oil production was sold too cheaply. I discussed this phenomenon in my 2009 piece, The Fate of An Oil Exporter. By contrast, one of the few modern states that has spoken openly about husbanding scarce energy resources is Brazil. President Lula declared in 2009, as Brazil changed its resources policy that year, that the country’s new offshore discoveries were a “passport to the future.” Misunderstood by right-leaning commentary at the time as a form of resource-nationalism, Lula’s remarks were instead very much in the Hotelling vein. “We don’t have the right to take the money we’re going to get with this oil and waste it,” Lula remarked. But Brazil has been an exception.

Given that both gold and oil production are now either flat or falling, what should a producer of these two commodities do with the proceeds of their sales? Let’s again consider the insurmountable problem at hand. Western economies and especially the United States have been on a credit binge for decades. When that bubble burst in 2008, punctured in large part by rising energy prices, the response from OECD governments was to create more credit. In Eric Zencey’s terrific New York Time’s essay on Frederick Soddy, which captured the views of the 1921 Nobel Laureate, the connection between debt limits and energy supply was made plain for a general readership:

Problems arise when wealth and debt are not kept in proper relation. The amount of wealth that an economy can create is limited by the amount of low-entropy energy that it can sustainably suck from its environment — and by the amount of high-entropy effluent from an economy that the environment can sustainably absorb. Debt, being imaginary, has no such natural limit. It can grow infinitely, compounding at any rate we decide.

Whenever an economy allows debt to grow faster than wealth can be created, that economy has a need for debt repudiation. Inflation can do the job, decreasing debt gradually by eroding the purchasing power, the claim on future wealth, that each of your saved dollars represents. But when there is no inflation, an economy with overgrown claims on future wealth will experience regular crises of debt repudiation — stock market crashes, bankruptcies and foreclosures, defaults on bonds or loans or pension promises, the disappearance of paper assets.

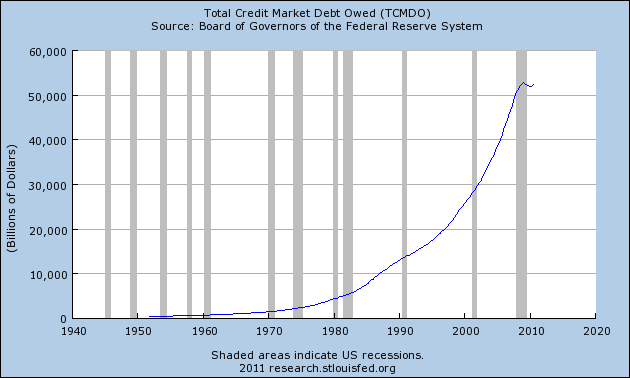
To Soddy’s point on the problem of infinitely created debt, let’s take a look at 60 years of debt growth in the United States. | see: Total Credit Market Debt Owed 1940 – 2010 (updated through December 2010).

As the United States has now (long) embarked on a massive dollar devaluation program, in part to bust the CNY-USD peg, but mostly to mitigate the next leg down in real-estate and debt deflation, we should consider how resource extractors might behave in such an environment. Two obvious possibilities are as follows. First, oil producers rather than chasing higher prices in dollar-terms might start to demand full or partial payment in gold. Meanwhile, gold producers might consider banking some of their capital not in cash, but also in gold. And yes, both oil and gold producers could simply leave more of the stuff in the ground. What may become more clear is that, beyond the need for operational cash, turning excess production of resources into paper currency will increasingly become, per Hotelling, a losing proposition.

Data Sources:

USGS Historical Statistics for Mineral and Material Commodities in the United States (includes global data).

Economic Research: Federal Reserve Bank of St Louis.

Posted in Gold & Silver | Comments Off on The case for Gold

Predictions by scientists and engineers

Charles A. Hall and David J. Murphy.  Predictions for 2011

We predict (with relatively little certainty assigned to it) that there will continue to be (for a while) a mild economic recovery, which will increase the demand for oil, and thus require the increased use of higher-priced oil. This will eventually require that 10 percent or so of the US GDP will go to the price of energy, which, as in the past, will lead to an economic downturn which will lead, in time, into the same cycle again. While we are not sure of the details of timing or prices we think that Jean Laherrere’s and Colin Campbell’s concept of the “undulating plateau” will continue to describe the US (and European) economies for the forseeable future — at least until serious peak oil and declining EROI kicks in.

Mid-East unrest could increase global phosphorus threat

Feb 2 2011 Terry Clinton University of Technology Sydney

Two Australian experts, Professor Stuart White and Dr Dana Cordell, in global phosphorus have warned instability in the Middle East and North Africa could threaten world food security, due to the high proportion of global phosphate rock reserves in the region.

Phosphorus is required to produce fertilizer and is not able to be substituted in food production.

Morocco alone controls the vast majority of the world’s remaining high quality phosphate rock,” Professor White said. “Even a temporary disruption to the supply of phosphate on the world market can have serious ramifications for nations’ food security.”

Professor White and Dr Cordell, from the Institute for Sustainable Futures at the University of Technology, Sydney, are leading an international research initiative on the likely peak in phosphate rock production before the end of the century.

“Demand for phosphorus is increasing globally due to changing diets in developing countries, biofuel production and population growth,” Professor White said.

“Peak phosphorus is often highly misunderstood as the ‘year we will run out of phosphorus’. The peak actually refers to the point in time when production will no longer be able to keep up with demand due to economic and energy constraints. Whilst the exact timeline is uncertain, it will be much sooner than the time when all the reserves have been depleted. Even before the peak in production occurs, there is the prospect of significant price spikes and impact on farmers and global crop yields.”

“The solutions rest in improving the efficiency of use, as much of the phosphate resource is wasted between the mine and the dinner plate,” Dr Cordell said. “No governments have a plan for securing sufficient access to phosphorus for producing food in the long-term. Whatever the exact year of peak phosphorus, it is clear we need to start taking action now. This means investing in renewable phosphorus fertilizers (by recovering and reusing phosphorus from our excreta, manure and food waste) and increasing the efficiency of phosphorus use from mining to fertilizer application to food processing.

Posted in Scientists | Comments Off on Predictions by scientists and engineers

Why the USA can’t inflate its way out of debt.

Mar 11, 2010. Why the U.S. can’t inflate its way out of debt. Financial Times.

It’s dawning on people that getting a handle on burgeoning U.S. debt will be a long and hard process. So if lawmakers can’t agree on a credible plan, some have suggested that the country could just “inflate its way” out of its fiscal ditch by boosting prices and wages and eroding the value of the currency. The United States would owe the same amount of actual dollars to its creditors — but the debt becomes easier to pay off because the dollar becomes cheaper.

It’s true that inflation could reduce a small portion of U.S. debt. The International Monetary Fund (IMF) estimates that in advanced economies less than a quarter of the anticipated growth in the debt-to-GDP ratio would be reduced by inflation. But the mother lode of the country’s looming debt burden would remain and the negative effects of inflation could create a whole new set of problems.

  1. A lot of government spending is tied to inflation. If inflation rises, so do government obligations, like Social Security, Medicare, and other are indexed.
  2. Inflation would also make future U.S. debt more expensive, because inflation tends to push up interest rates. And the Treasury will have to refinance $5 trillion worth of short-term debt between now and 2015. [The debt’s value could go down for a couple of years because of surprise inflation. But then … the market’s going to charge you a premium interest rate and say ‘you fooled us once but this time we’re going to charge you a much higher rate on your three-year bonds’.
  3. Another potential concern: Treasury inflation-protected securities (TIPS), which have maturities of 5, 10 and 20 years. They make up less than 10% of U.S. debt outstanding currently, but the Government Accountability Office has recommended Treasury offer more TIPS as part of its strategy to lengthen the average maturity on U.S. debt. The higher inflation goes, of course, the more the Treasury will owe on its TIPS.
  4. What’s more, the knock-on effects of inflation are not pretty. A recent report from the IMF outlined some of them: reduced economic growth, increased social and political stress and added strain on the poor — whose incomes aren’t likely to keep pace with the increase in food prices and other basics. That, in turn, could increase pressure on the government to provide aid — aid which would need to keep pace with inflation.

So where does that leave lawmakers? Facing tough choices. Deficit hawks and market experts have been calling on lawmakers to come up with a strategy to stabilize the growth in U.S. debt, which would be implemented only after the economy recovers more fully. The idea is to signal to the markets that the country is serious about getting its longer term debt under control so that the burden of paying it back doesn’t consume an ever-increasing share of the federal budget.

The recommended exit strategies are pretty basic, if unpopular: tax increases and spending cuts. Economic growth will play a key role as well — since a strong economy produces more tax revenue. But the country cannot grow its way out of its problems. To do that, the economy would have to expand at Herculean rates annually from here on out. And even the most optimistic economist doesn’t see that on the horizon.

Posted in Debt | Comments Off on Why the USA can’t inflate its way out of debt.

Richard Heinberg – collapse in a few years to decades

China or the U.S.: Which Will Be the Last Nation Standing?

Feb 3, 2010 by Richard Heinberg

Silly me. Here I had thought that world leaders would want to keep their nations from collapsing. They must be working hard to prevent currency collapse, financial system collapse, food system collapse, social collapse, environmental collapse, and the onset of general, overwhelming misery—right? But no, that’s not what the evidence suggests. Increasingly I am forced to conclude that the object of the game that world leaders are actually playing is not to avoid collapse; it’s simply to postpone it a while so as to be the last nation to go down, so yours can have the chance to pick the others’ carcasses before it meets the same fate.

I know, that sounds unbearably cynical. And in fact it may not accurately describe the conscious attitudes of leaders of some smaller nations. But for the U.S. and China, arguably the countries most likely to lead the way for the rest of the world, actions speak louder than words.

For these two nations, avoiding collapse would require solving a range of enormous problems, of which at least four are non-negotiable: climate change; peak fossil fuels (in effect, stagnating and, soon, declining energy supplies); the inherent instability of growth-based financial systems; and the vulnerability of food systems to factors like fresh water scarcity and soil erosion (in addition to global warming and fuel scarcity). If they fail to address any one of these, societal collapse is inevitable—in a few decades certainly, but perhaps in just the next few years.

So how are our contestants doing? There’s not much to report on the climate score—just vague promises for future action. So their apparent strategy in this case is to delay (not to delay the impacts, mind you, but to delay efforts to address the problem).

Likewise, there is little positive action occurring regarding food systems: the assumption appears to be that conventional industrial agriculture—which is responsible for most of the global food system’s enormous and growing vulnerabilities—will somehow shoulder the task of feeding seven to nine billion humans. We just need to continue with what we are already doing, but on a larger scale and using more gene-engineered crop varieties.

Officially, peak energy is not even a concern, so evidently the strategy being adopted here is denial. We’ll see how that works out.

How about the financial mess? Here the U.S. and China are in situations so different that a more extended discussion seems justified.

China Surges to the Lead!

The U.S. is in debt up to its eyeballs and has mortgaged the paychecks of every generation approximately until hell freezes over in order to bail out its “too-big-to-fail” banks. In contrast, China has piles of cash (resulting from its enormous trade surpluses) and has bought a mountain of U.S. debt in order to keep its main customer’s currency from losing value. It would seem that, in this department, one nation is set to flag while the other is poised to leap into first place as world economic superpower.

And that happens to be the conventional wisdom on the subject. It’s not hard to find commentators who say the United States is a has-been for a variety of reasons. In addition to its huge debt burden, the U.S. also suffers from a shrinking manufacturing base, a big trade deficit, eroding quality of education, and a foreign policy that serves the interests of arms manufacturers while undermining the long-term interests of the nation. Regarding the last of these items, a 2006 World Public Opinion poll showed large majorities in four leading ally nations (Egypt, Morocco, Pakistan, and Indonesia), together accounting for a third of the Muslim world’s population, believe the U.S. is determined to destroy or undermine Islam. Within those countries, most people surveyed support attacks on American targets. And it just so happens that most of the world’s future oil supplies will be coming from Muslim nations. Brilliant.

By contrast, China is enjoying springtime on amphetamines. It now has the biggest car market in the world. And, according to Stuart Staniford, “if present trends continue, the Chinese expressway system will grow larger than the U.S. interstate highway system within the next couple of years, and Chinese car ownership will exceed U.S. car ownership in 2017.” As of 2010 China is the leading producer of hydroelectric and solar power and by 2011 will be the top producer of wind power. China’s smart grid investments dwarf those of the U.S. by 200 to one. The Chinese are also investing heavily in nuclear energy. Staniford goes on: “Oversimplifying greatly, it’s as though the U.S. borrowed a pile of money from China in order to fight a war to free up oil supply in Iraq in order that China could become the greatest industrial power the world has ever seen.”

China’s foreign policy consists largely of buying friends by purchasing rights to oil, gas, coal, and other resources (in Canada, Australia, Venezuela, Iraq, Kazakhstan, and throughout Africa), while the U.S. spends money it doesn’t have rooting out bad guys and making more enemies in the process.

In an October, 2009 lecture, George Soros showed refreshing candor about the seriousness of the continuing global financial crisis: “What differentiated [the recent economic crisis] from the Great Depression is that this time the financial system was not allowed to collapse, but was put on artificial life support.  The magnitude of the credit and leverage problem we have today is even greater than the 1930s.” Soros then went on to discuss the relative positions of the U.S. and China:

In the short term, all countries were negatively affected. But in the long term, there will be winners and losers. . . . To put it bluntly, the U.S. stands to lose the most, and China is poised to emerge as the greatest winner. . . . China has been the primary beneficiary of globalization, and it has been largely insulated from the financial crisis. For the West, and the U.S. in particular, the crisis was an internally-generated event [that] led to the collapse of the financial system. For China, it was an external shock [that] has hurt exports, but left the financial, political, and economic system unscathed.

China Stumbles!

But remember: without solutions to climate change, peak energy, and the looming food crisis, winning the financial contest is only temporary solace. Consider just the energy conundrum: China may be building nukes and windmills, but there’s no way it can maintain 8% annual growth for long with flat or declining energy from coal. China and India, between them, are currently planning to build 800 new coal-fired power plants by 2020. Where will the coal come from? Both countries are already experiencing domestic production shortfalls and are starting to import the fuel. But coal-exporting countries will be unable to keep up with their growing combined demand.

Moreover, there is a school of thought that says China’s apparently unstoppable economic miracle is a bubble waiting to burst. Beijing’s housing market is overheated, like that of Las Vegas circa 2006. Last year, the Chinese economy enjoyed 9% GDP growth—on paper. But in order to achieve that goal, the government and banks had to loan out 30% of China’s GDP (the rate of growth in loans accelerated during the latter part of the year; at year-end rates, banks were on track to loan out an amount equal to the nation’s entire GDP in 2010). In any case, much of that growth probably occurred through speculation on real estate and questionable stocks.

Generally, China is at a Wild West stage of economic development: it is a collection of powerful local capitalist power bases unaccountable to anyone, all jockeying to create and inflate assets and credit. While the central government has recently exerted control over the banks, its ability to halt regional Ponzi schemes is still limited.

In January the Chinese banking regulatory commission attempted to rein in lending in order to slow the rapid increase in real estate and stock market values. (On the other hand, during the same month, China’s cabinet agreed to permit margin trading and short selling of stocks and to launch a stock futures index.) Significantly, there is evidence that China’s central bank’s attempts to harmlessly deflate the housing and stock market bubbles may be going badly. The sudden suspension in lending has, according to Joe Weisenthal in Business Insider, “caught importers, along with many other companies, by surprise and could cause turbulence in China’s import orders. Letters of credit (LoC) suddenly became unavailable, despite previous agreements. We believe that this will inevitably lead to delays or cancellations in China’s imports. Import orders for commodities and machineries could be affected most.” Translation: the government was faced with the options of letting a rapidly growing bubble burst, taking the economy down; or deliberately deflating the bubble, risking taking the economy down by another route. The central bank chose the latter, and the risked takedown may be unfolding.

In a recent op-ed, New York Times columnist Tom Friedman countered worries about a bursting of the China bubble with a robust display of confidence in Beijing’s unstoppable expansionary momentum. Given Friedman’s record (remember his columns in 2003 extolling the benefits that would flow to America from an invasion of Iraq?), this alone should be cause to doubt whether the Chinese locomotive can stay on its tracks much longer.

What Does It Mean to “Win”?

In his book Reinventing Collapse: The Soviet Example and American Prospects, Dmitry Orlov discusses the “collapse gap” between the United States and the old Soviet Union: the latter, he argues, was in effect much better prepared for economic crisis and the fall of its central government; when the U.S. eventually goes the way of the U.S.S.R., the pain and suffering of its citizens will be much greater. (I can’t adequately summarize Orlov’s evidence and reasoning here, but they are persuasive; if you haven’t read the book, do yourself a favor.)

So: How is the U.S. doing today in terms of collapse preparedness as compared to China?

After six decades of nearly uninterrupted economic growth, Americans have developed unrealistic expectations about the future. They are urbanized consumers whose manufacturing capability has shriveled and whose practical survival skills are in most cases vestigial. The Chinese, in contrast, have less of a steep fall ahead of them. Most still dwell in the countryside, and many who live in the cities are only one generation removed from subsistence agriculture and can still draw on their own, or their parents’, practical skills learned during decades of poverty and immersion in a traditional farming culture.

Both nations face fierce political challenges. In the U.S., the central government has reached nearly complete paralysis: it is evidently incapable of solving even relatively minor problems, and confidence in it among the citizenry has largely evaporated. Political leaders have succeeded in polarizing the people geographically with “hot-button” issues, few of which have anything to do with the factors currently undermining the nation’s ability to survive. The Chinese central government appears far more capable of acting decisively and strategically, but it is confronted with nasty facts of geography and history: there is an extreme and growing economic and social division between the wealthy coastal cities and the poor, rural interior; and a demographic schism between those 40 years old or younger who have high economic expectations, and the older generation who grew up under Mao, with an ethic of collectivism and self-sacrifice. The young, especially, have accepted a trade-off between civil freedoms and economic prosperity. If the latter is not delivered, there will be shrill demands for the former. These divisions are so deep and profound that they could tear society apart if expectations are dashed—and the leaders know this.

Thus, in the event of collapse, both nations face the possibility of a breakdown in their political systems, entailing widespread violence (uprisings and crackdowns).

China still maintains a crucial advantage in one key area: its food system. Far more of its citizens still grow food, even taking into account recent trends toward rapid urbanization (in the U.S., full-time farmers make up only about 2% of the population and the average farmer is approaching retirement age). This is not to say that China will have the capacity to feed all its people. The key difference has to do with the resiliency of the two nations’ respective food systems: that of the United States is more centralized, more highly fuel dependent, and therefore probably more vulnerable.

The Geopolitics of Collapse

It’s easy to see the advantage of collapse preparedness for the citizenry—with better preparation, more will survive. But does a higher survival rate during and after collapse translate to some sort of geopolitical advantage?

The process of collapse will be determined by many factors, some hard to predict, and so it is difficult to know the size or scope of the political power structure that might re-emerge in either country. It’s possible that one nation, or both, could devolve into smaller political units squabbling among themselves and unable to engage much in global jockeying for resources. All new political units emerging within the present territories of China or the U.S. would be immediately beset with enormous practical problems, including poverty, hunger, environmental disasters, and mass migrations.

Presumably some potent weaponry from the age of global warfare would remain intact and usable, so it is possible in principle that one or another of these smaller political entities could assert itself on the world stage as a short-lived, bargain-basement empire of limited geographic scope. But even in that case “winning” the collapse race would be small comfort.

The possibility of armed conflict between the two powers prior to mutual collapse is not to be entirely excluded if, for example, U.S. efforts to contain Iran’s nuclear ambitions were to set off a deadly chain reaction of attacks and counter-attacks possibly involving Israel, with world powers being forced to choose sides; or if the U.S. were to persist in arming Taiwan. But neither the U.S. nor China wants a direct mutual military confrontation, and both nations are highly motivated to avoid one. Thus all-out nuclear war—still the worst-case imaginable scenario for homo sapiens and planet Earth—seems thankfully unlikely, though in the few decades ahead the use of some of these weapons, on some occasions, by one nation or another, is probable.

Trade wars are another matter, and we might even see one this year, according to Michael Pettis at Financial Times, who notes that

. . . trade imbalances are more necessary than ever to justify increased investment in surplus countries [i.e., China], but rising unemployment makes them politically and economically unacceptable in deficit countries [i.e., the U.S.]. Rising savings in the U.S. will collide with stubbornly high savings in China. Unless a long-term solution is jointly worked out immediately, trade conflict will worsen and it will become increasingly hard to reverse offensive policies. Most importantly, if deficit countries demand structural change faster than surplus countries can manage, we will almost certainly finish with a nasty trade dispute that will . . . poison relationships for years.

How likely is the prospect for the last nation standing to be able to, as I put it in the first paragraph above, “pick the carcasses” of its competitors? Such a scenario presupposes that one nation will be able to stay on its feet for at least a few years after others fall. But this may not be possible. Recall the prophetic words of Joseph Tainter in The Collapse of Complex Societies (1988):

“A nation today can no longer unilaterally collapse, for if any national government disintegrates, its population and territory will be absorbed by some other [or bailed out by international agencies]. . . . Collapse, if and when it comes again, will this time be global. No longer can any individual nation collapse.”

When the U.S.S.R. crashed, the U.S. and various multinational corporations were able to sweep in and gobble up some of the treasure left lying around. One example: U.S. nuclear power plants have for many years been using uranium fuel cannibalized from old Soviet missile warheads. Soon, international institutions such as the World Bank and IMF helped organize new financial structures for Russia, Ukraine, Belarus, Lithuania, Estonia, and the other nations born from Soviet political and economic disintegration, so as to limit and reverse the process of social disintegration that had already passed beyond its early stages.

But now the game has changed. A collapse of the U.S. would leave China devastated. Not only would Beijing lose its main customer, but the hundreds of billions of dollars’ worth of treasury notes it has accumulated would be rendered worthless. If China were internally stable, such impacts could be absorbed with difficulty. But in light of China’s own simmering social and financial predicaments, a U.S. collapse would almost certainly be enough to tip Beijing’s economy into a tailspin, resulting in both social and political crises.

A collapse of China would similarly devastate the U.S.

In neither instance would international institutions be capable of preventing substantial social and political fall-out. The last nation standing would not stand for long. We have reached the stage where, as Tainter says, “World civilization will disintegrate as a whole.”


The Transition Marathon

Okay, so there is no serious effort on the part of U.S. or Chinese leaders to avoid collapse in the long run (over the next 10 to 20 years). Perhaps this is because they have concluded that it is impossible to do so—there are just too many trends leading in the same direction, and actually dealing with any of those trends head-on would entail huge, immediate political risks. In reality, however, it is much more likely that they simply refuse seriously to think about these trends and their implications, because they do have another option—to postpone collapse through deficit spending, bailouts, and more financial bubbles, while enacting their parts in a climate-policy kabuki play and engaging in resource geopolitics. This way blame will at least fall on the next set of leaders. Postponing collapse is itself a big job, enough so as to take all of one’s attention away from having to contemplate the awfulness and inevitability of what is being postponed.

Do these short-term efforts in any way reduce the risk of dissolution? Hardly. In fact, the longer the reckoning is delayed, the worse it will be.

What would make more sense than just trying to put off the inevitable is quite simply to build resilience throughout society, re-localizing basic social systems involving food, manufacture, and finance. There is no need to rehearse the existing discourse about this strategy: readers who are not familiar with it can find plenty of useful pointers at www.transitiontowns.org, or in the books and articles of authors such as Rob Hopkins, Albert Bates, David Holmgren, Pat Murphy, and Sharon Astyk (and in some of my own writings, including Museletter #192).

It is understandably hard for national politicians to think along those lines. Building societal resilience means disregarding the dictates of economic efficiency; it means systematically reducing the power of the central government and national/global commercial institutions (banks and corporations). It also means questioning the central dogma of our modern world: the efficacy and possibility of unending economic growth.

So if the best outcome lies in a strategy of resilience and re-localization, and our national leaders can’t even contemplate such a strategy, that means those leaders are, in one sense at least, irrelevant to our future.

Some blog readers are so in tune with this line of thinking that they no longer see any point in paying attention to the global scene. They may even think this article is a waste of time (and I expect to get an email or two to that effect). But following world events is more than a matter of infotainment: when and how China and the U.S. come apart at the seams is a question of far greater consequence than that of whether the New Orleans Saints or the Indianapolis Colts will win the Superbowl. The reality is that no nation, and no community will be able to completely protect itself from the sudden, harsh winds that will rush to fill the vacuum left by an implosion of either superpower.

By the way, my apologies to the other 190 or so nations of the world, large and small: my singling out of the U.S. and China for discussion does not signify that other countries are unimportant, or that their destinies will not be as unique as their cultures and geographies; merely that those destinies will probably unfold in the context of a global collapse spreading from the two nations we have been discussing. For any nation—India, Bolivia, Russia, Brazil, South Africa—and for any community or family, survival will require some comprehension of the direction of large events, so as to get out of the way when debris is flying and to anticipate opportunities to regroup.

So: Pay attention to the weather reports from Washington and Beijing, but meanwhile build local resilience wherever you are. If the roof needs mending, don’t dawdle.

Just because the sky is falling, that doesn’t mean it’s time to stop thinking.
Posted in By People, Richard Heinberg | Comments Off on Richard Heinberg – collapse in a few years to decades

Paul Kingsnorth on Collapse

It’s the End of the World as We Know It . . . and He Feels Fine

APRIL 17, 2014  DANIEL SMITH    New York Times

[excerpts from a very long article]

Kingsnorth is 41, tall, slim and energetic, with sweeping brown hair and a sparse beard… often apologizing for having said too much or for having said it too strongly.

The forces at play are enormous. The time for ‘facing the difficulties’ was decades ago. Despair is, frankly, the only option because there are no other options.

The “human machine,” as he sometimes puts it, has grown to such a size that breakdown is inevitable.

The Dark Mountain Project was founded in 2009. From the start, it has been difficult to pin down — even for its members.  When you ask Kingsnorth about Dark Mountain, he speaks of mourning, grief and despair. We are living, he says, through the “age of ecocide,” and like a long-dazed widower, we are finally becoming sensible to the magnitude of our loss, which it is our duty to face.

Kingsnorth himself arrived at this point about six years ago, after nearly two decades of devoted activism.

At the same time, he felt his longstanding faith in environmental activism draining away. “I had a lot of friends who were writing about climate change and doing a lot of good work on it,” he told me during a break from his festival duties. “I was just listening and looking at the facts and thinking: Wow, we are really screwed here. We are not going to stop this from happening.

The facts were indeed increasingly daunting. The first decade of the 21st century was shaping up to be the hottest in recorded history. In 2007, the Arctic sea ice shrank to a level not seen in centuries. That same year, the NASA climatologist James Hansen, who has been ringing the climate alarm since the 1980s, announced that in order to elude the most devastating consequences, we’d need to maintain carbon dioxide in the atmosphere at a level of 350 parts per million. But we’d already surpassed 380, and the figure was rising. (It has since reached 400 p.p.m.) Animal and plant species, meanwhile, were dying out at a spectacular rate. Scientists were beginning to warn that human activity — greenhouse-gas emissions, urbanization, the global spread of invasive species — was driving the planet toward a “mass extinction” event, something that has occurred only five times since life emerged, 3.5 billion years ago.

“Everything had gotten worse,” Kingsnorth said. “You look at every trend that environmentalists like me have been trying to stop for 50 years, and every single thing had gotten worse. And I thought: I can’t do this anymore. I can’t sit here saying: ‘Yes, comrades, we must act! We only need one more push, and we’ll save the world!’ I don’t believe it. I don’t believe it! So what do I do?

The first thing that Kingsnorth did was draft a manifesto. Also called “Uncivilization,” it was an intense, brooding document that vilified progress. “There is a fall coming,” it announced. “After a quarter-century of complacency, in which we were invited to believe in bubbles that would never burst, prices that would never fall . . . Hubris has been introduced to Nemesis.”

The initial print run of “Uncivilization” was only 500 copies. Yet the manifesto gained widespread attention. The philosopher John Gray reviewed it in The New Statesman. Professors included it on their reading lists.  Doug Tompkins, the billionaire who started the outdoor-apparel company the North Face, and his wife, Kristine Tompkins, the former C.E.O. of Patagonia,  invited Kingsnorth and his family to spend two months on land they own in southern Chile.

Kingsnorth’s was branded a “doomer,” “nihilist” and “crazy collapsitarian.”

Kingsnorth regards such charges with equanimity, countering that the only hope he has abandoned is false hope. The great value of Dark Mountain, he has claimed, is that it gives people license to do the same. “Whenever I hear the word ‘hope’ these days, I reach for my whiskey bottle,” he told an interviewer in 2012. “It seems to me to be such a futile thing. What does it mean? What are we hoping for? And why are we reduced to something so desperate? Surely we only hope when we are powerless?

Instead of trying to “save the earth,” Kingsnorth says, people should start talking about what is actually possible. He insists that he isn’t opposed to political action, mass or otherwise, and that his indignations about environmental decline and industrial capitalism are, if anything, stronger than ever. Still, much of his recent writing has been devoted to fulminating against how environmentalism, in its crisis phase, draws adherents. Movements like Bill McKibben’s 350.org, for instance, might engage people, Kingsnorth told me, but they have no chance of stopping climate change. “I just wish there was a way to be more honest about that,” he went on, “because actually what McKibben’s doing, and what all these movements are doing, is selling people a false premise. They’re saying, ‘If we take these actions, we will be able to achieve this goal.’ And if you can’t, and you know that, then you’re lying to people. And those people . . . they’re going to feel despair.

Kingsnorth would agree with the need for grief but not with the idea that it must lead to change — at least not the kind of change that mainstream environmental groups pursue. “What do you do,” he asked, “when you accept that all of these changes are coming, things that you value are going to be lost, things that make you unhappy are going to happen, things that you wanted to achieve you can’t achieve, but you still have to live with it, and there’s still beauty, and there’s still meaning, and there are still things you can do to make the world less bad? And that’s not a series of questions that have any answers other than people’s personal answers to them. Selfishly it’s just a process I’m going through.” He laughed. “It’s extremely narcissistic of me. Rather than just having a personal crisis, I’ve said: ‘Hey! Come share my crisis with me!’

For Kingsnorth, the notion that technology will stave off the most catastrophic effects of global warming is not just wrong, it’s repellent — a distortion of the proper relationship between humans and the natural world and evidence that in the throes of crisis, many environmentalists have abandoned the principle that “nature has some intrinsic, inherent value beyond the instrumental.”

When Kingsnorth describes how he came to this way of thinking, he nearly always begins with an ancient chalk hill outside Winchester, not far from the site of the recent Uncivilization festival. It was 1992, and the conservative British government was about to break ground on a vast network of highways across England.

The highways were proposed three years earlier by Margaret Thatcher, whose administration announced that they would constitute the “biggest road-building program since the Romans.” As it happened, they would also cut through areas that had remained unspoiled since the Romans. Direct opposition to the program began at a hill called Twyford Down, through which the government planned to build a six-lane highway. The purpose of the road was to reduce the commute to London by a matter of minutes. In 1992, a small band of radicals calling themselves the Dongas staged a demonstration. Soon road protests were popping up across the country, drawing support from itinerant hippies, the working classes and the nobility.  The core of the demonstrators’ complaints was not that the new highways would worsen air pollution, cause car accidents or fracture communities; it was that some things, like wilderness and beauty, were — despite, or perhaps because of, their “uselessness” — more important than getting to work on time.

At a time when the Great Depression was destroying millions of lives and Europe was militarizing for a new war, poet Robinson Jeffers saw human history as an inexorable, almost naturally destructive force. “The beauty of modern/Man is not in the persons,” he wrote in “Rearmament,” a poem that became the epigraph for “Uncivilization,’, “but in the/Disastrous rhythm, the heavy and mobile masses, the dance of the/Dream-led masses down the dark mountain.

Each man draws a distinction between a “problem,” which can be solved, and a “predicament,” which must be endured. “Uncivilization” was firm in its conviction that climate change and other ecological crises are predicaments, and it called for a cadre of like-minded writers to “challenge the stories which underpin our civilization: the myth of progress, the myth of human centrality and the myth of separation from ‘nature.’;

Hine compared coming to terms with the scope of ecological loss to coming to terms with a terminal illness. “The feeling is a feeling of despair to begin with, but within that space other things begin to come through. Some people come here,” Hine told me, “they get very excited by the fact that people are inspired, and they go: ‘Right! Great! So what’s the plan?’ ” He and Kingsnorth have worked hard to check this impulse, seeing Dark Mountain as a space to set aside what Kingsnorth refers to as “activist-y” urges.

In a heated exchange with columnist George Monbiot, Kingsnorth argued that civilization was approaching collapse and that it was time to step back and talk about how to live through it with dignity and honor. Monbiot responded that “stepping back” from direct political action was equivalent to a near-criminal disavowal of one’s moral duty. “How many people do you believe the world could support without either fossil fuels or an equivalent investment in alternative energy?” he asked. “How many would survive without modern industrial civilization? Two billion? One billion? Under your vision, several billion perish. And you tell me we have nothing to fear.

On the surface, it can indeed seem as if Kingsnorth is giving up. Last week, he and his wife made a long-planned move to rural Ireland, where they will be growing much of their own food and home schooling their children — a decision, he explained to me, that stemmed in part from a desire to distance himself from technological civilization and in part from wanting to teach his children skills they might need in a hotter future. Yet Kingsnorth has never intended to retreat altogether. For the past three years, he has spent a good portion of his time trying to stop a large supermarket from being built in Ulverston, in northern England. “Why do I do this,” he wrote to me in an email, anticipating my questions, “when I know that in a national context another supermarket will make no difference at all, and when I know that I can’t stop the trend caused by the destruction of the local economy, and when I know we probably won’t win anyway?” He does it, he said, because his sense of what is valuable and good recoils at all that supermarket chains represent. “I’m increasingly attracted by the idea that there can be at least small pockets where life and character and beauty and meaning continue. If I could help protect one of those from destruction, maybe that would be enough. Maybe it would be more than most people do. “

Posted in By People | Comments Off on Paul Kingsnorth on Collapse

Banks still gambling on illegal Collateralized Loan Obligations (CLO)

Banks Cling to Bundles Holding Risk

APRIL 19, 2014 GRETCHEN MORGENSON New York Times

Some $431 billion worth of C.L.O.s currently exist.

The Volcker Rule doesn’t go into effect until 2015, but that hasn’t stopped big bankers and their supporters in Washington from trying to undermine it.  The Volcker Rule was intended to bar banks with insured deposits from making large and risky trading bets. The rule was lawmakers’ attempt to reinstate some of the taxpayer protections lost when Congress gutted the Glass-Steagall Act in 1999.

The latest fight involves another complex Wall Street creation, a financial instrument known as a collateralized loan obligation. Big banks want to be allowed to own them but regulators say such holdings can be hazardous and may allow the banks to evade the Volcker Rule’s prohibition on risky trading.

There have been countless battles over the Volcker Rule since it was first conceptualized in the Dodd-Frank law in 2010. Paul A. Volcker, the former Federal Reserve chairman for whom the rule is named, hasn’t talked about most of these fights, but this one is important enough that he has come forward to discuss it.

“This constant effort to get around the rule limiting banks’ investment in hedge funds, on behalf of a few institutions who apparently want room to resume the financing practices that got us into trouble in the past, really should end,” Mr. Volcker said in a statement last week.

Read the entire article here.

What are collateralized loan obligations, or C.L.O.s? Translated into simple English, they are bundles of mostly commercial loans that are sold in various pieces to investors. They are similar to collateralized debt obligations, or C.D.O.s — those instruments that imperiled so many institutions in 2008

Posted in Banking | Comments Off on Banks still gambling on illegal Collateralized Loan Obligations (CLO)

Have Cash by Nicole Foss July 3, 2010

Since we at The Automatic Earth generally tell people to hold cash or cash equivalents, it makes sense to expand on that a little, and to point out some of the location-specific risks of doing so.

Eventually you should get into hard assets, even if asset prices still have further to fall. Liquidity can be as hard to hang on to as it sounds, and is therefore not a long term bet. A couple of years should be enough to ride out the worst of an asset price collapse while still being in a relatively low risk position regarding liquidity

But for now, we tell people to hold cash because that is what they will need access to in order to make debt payments and to purchase the essentials of life in a society with little or no remaining credit. The value of cash domestically – in terms of goods and services in your own local area – is what matters most.

Domestic currency value relative to other currencies internationally will be very much a secondary concern for most people, as the ability to exchange one currency for another is not likely to last far into the coming era of capital controls. Currency risk is likely to become very large, and almost everyone will be better off holding whatever passes for cash wherever they happen to be.

As the price of goods and services fall, thanks to the destruction of purchasing power brought about by collapsing money supply, what cash you still have will go a lot further in terms of, say, milk and bread. Capital preserved as liquidity will go a long way. However, there are NO no-risk scenarios. Apart from the obvious risks of fire, flood and theft, other risks to holding cash will grow over time. Liquidity can be as hard to hold on to as it sounds.

One particular risk is the reissuing of currency. Russia did this during the economic collapse of the Soviet Union, and made it so difficult for ordinary people to convert old currency into new that much of the middle class lost their life-savings. In Russia trust in relation to banks was not particularly high, hence there was a lot of money under the beds of the nation that the powers-that-be were attempting to flush out. That is not the case in present day industrialized countries, where people generally believe that banks are safe and deposits are publicly guaranteed in any case.

Requiring people to convert would require them to reveal what they had though, and this would probably result in windfall tax bills (i.e. extortion) for those who had been foresighted.

On top of that, few people have savings, having become dependent on access to cheap credit for their rainy-day funds. There is virtually nothing under the beds of the Western nation, and so essentially nothing to flush out.

Although that particular rationale for currency reissue does not really exist (the flushing out of hidden wealth), there may be other reasons for doing so, and these will be locational. The risk of currency reissue in the US is likely to be low for some time. The US is likely to benefit from capital flight from other places, on a knee-jerk flight to safety.

In addition, dollar-denominated debt deflation will increase demand for dollars, and hence increase their value. This should reduce pressure for any kind of radical currency reform for a while. If the US does eventually reissue its currency, I would imagine them doing so in order to deprive foreign holders of dollars of purchasing power. There are very large numbers of dollars held overseas, and these would not be able to be exchanged in a currency reissue. At some point this may serve the interests of the US, but not soon.

The pros and cons of short-term T-bills

Negative t-bill rates will make cash on hand look better than bonds, even of the shortest duration, as cash won’t have a built in depreciation.


T-bills will still be a good deal relative to most things, but cash on hand will be better.


That will increase the likelihood of cash withdrawals leading to bank runs.


Welcome to the perfect financial storm


What is coming, I think, is a nominal short term interest rate that is moderately negative – an official Fed rate rather than a market rate as at present (as the Fed follows the market). This means people will be paying to own t-bills, but this will still be one of the best options available for short term capital preservation. The capital will be far less likely to be lost there than in a bank, and the return OF capital is the important thing. Despite a negative nominal rate, the real rate (the nominal rate minus negative inflation) will still be high as deleveraging continues and accelerates.

It won’t be as high as it would have been at a nominal rate of zero, but there would still be a real return on top of greater capital security than most other options. I think a lot of investors will be happy to buy t-bills even where the nominal rate is negative. The US dollar appreciation relative to other currencies will be a significant bonus as well.

Of course cash on hand would be an even better option in terms of return, because that would have a higher nominal rate, zero percent, and therefore a higher real rate as well. The real rate will apply even outside a bank, reflecting the greater domestic purchasing power of liquidity.

But it isn’t practical to hold really large sums of money in cash

Hard goods

Everyone will need to make the transition from cash to hard goods at some point. Cash is what you need to navigate the great deleveraging, but over the time the risks to cash will rise and you will need to think of the next phase, which is addressing the risk of the kind of economic upheaval that breaks supply lines. That will come first, and inflation (ie actual currency printing) will come much later. Inflation is only a risk once the power of the bond market has been broken, and that is not today’s risk, nor tomorrow’s.

That is something to consider much further down the line. Deflation and depression are mutually reinforcing in a spiral of positive feedback. That is not a dynamic that will end quickly, but end it will some day. At that point, or well before depending on where you live, you will want to be fully invested in hard goods.

Posted in Investing advice | Comments Off on Have Cash by Nicole Foss July 3, 2010

Fannie & Freddie started the mortgage crisis

Reckless Endangerment. How outsized ambition, greed, and corruption led to Economic Armageddon

2011 by Gretchen Morgenson and Joshua Rosner

This book makes the case that Fannie & Freddie started the mortgage crisis and then Wall Street got in on the game and enormously magnified the scale of the corruption and damage of the bubble.

Some reviews of this book in: the New York Times, USA Today, and the Washington Post.

Ilargi at theautomaticearth July 13, 2010

Fannie and Freddie are the main cause why home prices in the US have risen so high that millions of Americans are being evicted from their homes as we speak simply because they can’t afford to live in them anymore. Fannie and Freddie (and the FHFA and FHLB and Ginnie Mae) have been used to guarantee any mortgage at any price and at any liar’s conditions, and all at the risk of the American people.

Charles Hugh Smith sums it up very well, read it a few times, I’d recommend, though he’s got the time-frame wrong. It’s not the con of the decade, it’s the largest financial con ever perpetrated on the American people since 1776:

The Con of the Decade Part I

1. Enable trillions of dollars in mortgages guaranteed to default by packaging unlimited quantities of them into mortgage-backed securities (MBS), creating unlimited demand for fraudulently originated loans.

2. Sell these MBS as “safe” to credulous investors, institutions, town councils in Norway, etc., i.e. “the bezzle” on a global scale.

3. Make huge “side bets” against these doomed mortgages so when they default then the short-side bets generate billions in profits.

4. Leverage each $1 of actual capital into $100 of high-risk bets.

5. Hide the utterly fraudulent bets offshore and/or off-balance sheet (not that the regulators you had muzzled would have noticed anyway).

6. When the longside bets go bad, transfer hundreds of billions of dollars in Federal guarantees, bailouts and backstops into the private hands which made the risky bets, either via direct payments or via proxies like AIG. Enable these private Power Elites to borrow hundreds of billions more from the Treasury/Fed at zero interest.

7. Deposit these funds at the Federal Reserve, where they earn 3-4%. Reap billions in guaranteed income by borrowing Federal money for free and getting paid interest by the Fed.

8. As profits pile up, start buying boatloads of short-term U.S. Treasuries. Now the taxpayers who absorbed the trillions in private losses and who transferred trillions in subsidies, backstops, guarantees, bailouts and loans to private banks and corporations, are now paying interest on the Treasuries their own money purchased for the banks/corporations.

9. Slowly acquire trillions of dollars in Treasuries–not difficult to do as the Federal government is borrowing $1.5 trillion a year.

This part hasn’t happened yet, but still could:

10. Stop buying Treasuries and dump a boatload onto the market, forcing interest rates to rise as supply of new T-Bills exceeds demand (at least temporarily). Repeat as necessary to double and then triple interest rates paid on Treasuries.

11. Buy hundreds of billions in long-term Treasuries at high rates of interest. As interest rates rise, interest payments dwarf all other Federal spending, forcing extreme cuts in all other government spending.

12. Enjoy the hundreds of billions of dollars in interest payments being paid by taxpayers on Treasuries that were purchased with their money but which are safely in private hands.

Posted in Mortgages | Comments Off on Fannie & Freddie started the mortgage crisis

A book review of “Russia’s Food Policies and Globalization”

Preface.  Today Russia exports a substantial percent of wheat, and now that oil prices are surging is in much better shape than after the Fall of the Soviet Union in 1991.  But with peak oil likely in 2018, and money that should have gone into maintaining and drilling/exploration for oil having gone into bank accounts instead, it remains to be seen how long it will be before Russia begins energy descent.  Perhaps one reason for the invasion of Ukraine now rather than later.

Alice Friedemann  www.energyskeptic.com  Author of Life After Fossil Fuels: A Reality Check on Alternative Energy; When Trucks Stop Running: Energy and the Future of Transportation”, Barriers to Making Algal Biofuels, & “Crunch! Whole Grain Artisan Chips and Crackers”.  Women in ecology  Podcasts: WGBH, Planet: Critical, Crazy Town, Collapse Chronicles, Derrick Jensen, Practical Prepping, Kunstler 253 &278, Peak Prosperity,  Index of best energyskeptic posts

***

Governments that can’t feed their people lose their legitimacy and risk widespread social unrest.  The Russian government has made many mistakes in the past, such as with collectivization (which America has also done by policies that discouraged family farms in favor of mono-cropping industrial large-scale farming).  Russia has also had to cope with a very harsh climate, which has always affected production.

But because of the hard times for centuries, Russians are more prepared than highly functional, industrialized societies like America or Europe, because when times have gotten tough, many of Russia’s citizens have had access to garden plots.  In the 1980s, households that grew food consumed 90% of it and sold the other 10%.

Although the USSR modernized in fertilizer, machinery, food distribution, and post-harvest technology somewhat from 1964 to 1982, farms still had all kinds of shortages.  Large farms couldn’t fire drunks and slackers, nor hang onto skilled and hard-working laborers.  Adding to the confusion, over 11 different ministries oversaw food production.

The main Russian food policy for many decades has been to protect urban dwellers from the true cost of food, to the detriment of the rural sector.  Over 80% of subsidies to agriculture went to keeping the price of food in cities down.  Meanwhile the country had 100 million people, but only 10% of the electricity, no access to the gas network, poor roads, schools, medical services and so on.

Yet food production went up on average, though there were long lines, poor quality, and little selection in the cities due to an inadequate food distribution system.  But still, the USSR fed itself most of the time.

At the state controlled level, large farms mainly produced the grain, flax, sugar, beets, sunflower seeds, and a lot of the meat, milk, eggs, and wool, but only half of the vegetables and a quarter of the potatoes.

In the 1990-1991 food crisis, there was rationing and people resorted to buying very expensive food in the farmers markets that sprang up in cities.  From 1991 to 2002 food production went down 35-40% yet the population only went down 2.5%.  Food production went down and prices went up because less land was cultivated, less fertilizer and pesticide were used, there was more manual labor, and less farm equipment (especially since spare parts were expensive or not available), increased fuel, electricity, and transportation costs.  The years from 1992 to 1998 were the worst.  By 2002, 45 million families grew food on an average of 1 acre (up from half an acre in 1990).  By 1998, households produced 59% of the food grown (the ruble, not calorie value).

Rural families produced 46% of their food, in urban areas families could only provide 9%.  During this time the number of cattle and pigs went down to numbers lower than in 1943.

After price liberalization in 1992, inflation reached 2,600%, and again went up 900% in 1993.  Food prices skyrocketed.  A third of Russians were undernourished.  Hunger was prevalent among older people without sufficient pensions.  Food went from a third to half of urban budgets initially, and then as food production went up, down to 40% in 2000.  But low income families still experienced hunger and malnutrition.  The wealthier were still able to afford to eat meat.

In the worst year, 1998, rural people got a third of their food from what they could grow on their private plots – 3,216 calories per capita vs 2,612 for urbanites, as well as more protein and fat.  Rural people also had more bread, potatoes, vegetables, milk and milk products, and sugar than city dwellers did.

Among rural people, the wealthiest sold more of their home grown food and had more land than the poorer families.  The top 5% of families produced by far the most meat and fruit – the most expensive, valuable food to sell to cities.

The poor remained poor. They consumed all they grew, so they couldn’t sell extra food to accumulate capital to buy more land.

The average private plot of land was about 2100 square feet.  Men spent 10.5 hours and women 8.5 hours per week working the family plot, mainly for family food and not for sale from the 1960s through the 1980s.  In 1991 that acreage went up when 38 million put new plots on nearly 32,000 square miles of land.

Prices really needed to go up in urban areas to reflect the true cost of food production, but the government was so afraid of “social tension” that it wasn’t until April of 1991, for the first time in several decades, that prices went up.  Meat prices went up 200%, dairy 130%, eggs 100%, and bread 200%. But wages went up too.  Bread was subsidized until 1993.

From 1972 to 1991 the USSR accounted for 75% of USA agricultural exports of grain.  The USSR has never exported much food.  In 1991, 28% of Russian food was imported.

Some experts considered the food crisis starting in 1991 to be mainly due to the lack of post-harvest food handling facilities, because for about 6 years, the amount of grain lost to not being stored properly equaled the amount imported.

Grain is one of the most politically sensitive of all food products in the USSR because of the importance of bread in the culture, and even greater in the 90s when the standard of living dropped.

The cost of food went up an average of 5% per week in 1992 and 3% per week in 1993.  The feared social disorder didn’t happen because

1)      Moscow and Leningrad continued to get food – it was the 2nd and 3rd echelon cities that suffered

2)      Before the crash even successful people in the USSR could buy very little with their money, so few worked hard.  When high prices hit, so did the opportunities to make more money, and the appearance of luxury goods that hadn’t been available before, so people hoped that if they worked hard they could someday afford to buy expensive goods.

3)      There was still social protection.  Ceilings on price markups and profits from bread and flour were imposed.  Even in 2000, half of all Russian regions placed controls on prices of primary foods.

Cities like Kostroma were very innovative in coping with the crisis.  The city rented land from landowners and large farms for the poor to grow potatoes on.. The city also rented municipal land to grow food on at very low rates.  Those working on farms could buy their meals and groceries “at cost”, and at the next step up the food chain, food processing, employees could buy food at very little markup.  Restaurant employees got their main meal of the day at a discount.

Food expanded the use of barter – food could be traded for services, debt payments, and so on.  Stalls, kiosks, and urban markets selling food sprang up in new places.

In some regions, the local or regional government gave farmers fertilizer, oil, seed, and so on to grow grain but then insisted on a low price, often too low, to make sure their people had food, or sold the grain at a profit to other regions.   As state government control of agriculture decreased, regional control increased to make sure there was enough food for the people living in the region.  By 1999, 20 regional food markets existed with 30 more regions in the process of doing the same.

Russian oil and gas companies invested in food processing after the 1998 financial crash, which helped food processors recover.

Wheat was especially valued due to its nonperishable nature and in some respects became a substitute currency.  Growers used wheat as barter in 16% of transactions in 1995 and 25% in 1997.

Not much food was sold on commodity exchanges, only 3.3% of the wheat crop was sold this way in 2002.

Many advocated for vertical processing of food, with processors owning the farms, but this isn’t happening much, when it does, it’s in the Moscow or Leningrad area where consumers have greater purchasing power and money to invest.

Families growing a fair amount of wheat, meat, and other food often preferred to sell to the local government or a private company rather than directly to the public because they didn’t have enough time, surplus labor, or contacts to find buyers.

Despite all the pressure to go to a “market economy”, regional governments distrusted “the market” and regulated agriculture heavily to be sure people were fed.  Even in the worst times in 1998, the government made sure that they won the bids to distribute food – controlling food is a good way to stay in power.  This upset some political factions in the USA – we’d sent a lot of food over there and didn’t want this to aid the old guard in maintaining their power.

This book spends a lot of time explaining the history of food in Russia, because it’s trying to explain why it isn’t likely food will be exported from Russia in vast amounts any time soon.  Currently regional governments restrict how much food can be sold outside of the region to other regions within Russia to make sure their people are fed.  Farmers like this protection because they’re paid more since they’re protected them from outside competition.  There are 16 regions that forbid any export of food beyond their borders.  Governments, by lending them money for oil and other farm inputs can insist on this.

So opportunities for Wall Street and Russian capitalists to make lots of money from exporting Russian food globally is not a good way to grow rich now.  Plus Russia’s agricultural production is still low compared to USA or Europe because they’re less mechanized, experience fuel shortages, and have greater production costs.  Their scientists estimate that the biological potential of the agricultural land is 2.5 times less than the USA or EU on average.  So agriculture is protected – just as it is in the USA and EU with subsidies.

In the highest circles of government, Russians would prefer to have food security over importing cheap food and fight to continue to protect Russian agriculture, but it’s a delicate balance since they don’t want to have food prices so high that citizens can’t afford it – so the government helps the bottom 25-35% below the poverty line afford food.

The problems of the large farms – mainly the politics and bureaucracies that oversaw them, were so awful it’s amazing any food was ever produced

Posted in Agriculture, Oil shock collapse | Tagged , , | Comments Off on A book review of “Russia’s Food Policies and Globalization”

The need for trust

Beyond the Trust Horizon 

Oct 1, 2010  Nicole Foss   theautomatic earth

Relationships of trust are the glue that holds societies together. Trust takes a long time to establish, and much less time to destroy, hence societies where trust is wide-spread, particularly for long periods of time, are relatively rare. In contrast, societies where trust does not extend beyond the family, or clan, level are very common in history.

The spread of trust is a characteristic of expansionary times, along with increasing inclusion, and a weakening of the ‘Us vs Them’ divide. Essentially, the trust horizon expands, both within and between societies. Over time it can encompass higher levels of organization – from family to community to municipality to region to nation and beyond – so long as the expansionary dynamic continues to support it.

Within societies this leads to relatively stable and (at least temporarily) effective institutions, and bolsters the development of the rule of law. The rule of law means that law constrains the powerful (more than usual), and there is a reasonable degree of legal transparency and predictability, so that people are prepared to trust in the fairness and accessibility of justice. Naturally, the ideal is never reached, human nature being what it is, but it can be approached under the most favourable of circumstances.

Within societies, trust also confers political legitimacy (ie a widespread buy-in as to the right of rulers to rule). Where there is legitimacy, there is relatively little need for surveillance and coercion. A high level of trust (all the way up to the level of national institutions) is thus a prerequisite for an open society.

Between societies, an expansion of the trust horizon tends to lead to political accretion. Larger and more disparate groups feel comfortable with closer ties and greater inter-dependence, and are prepared to leave past conflicts behind. The European Union, where 25 countries with a very long history of conflicts have come together, is a prime example.

However, all expansions have a limited lifespan, as do the benefits they confer. They sow the seeds of their own destruction, especially when they morph into a final manic phase and begin to hollow out the substance of social structures. Institutions, whether public or private, retain the same outward form, but cease to operate as they once did. For a while it is possible to maintain the illusion of business as usual (or effectiveness and accountability as usual), but not indefinitely. Everything is subject to receding horizons eventually, and trust is no exception.

Over time institutions become sclerotic, unresponsive, self-serving and hostage to vested interests, at which point they cannot be reformed, as the reform would have to come from those entrenched individuals who have benefited most from the status quo. Institutions become demonstrably less effective, while consuming more and more of society’s resources. Corruption, abuses of power, lack of accountability and the loss of the rule of law become increasingly evident, exactly as we have seen with unauthorized wire-tapping, extra-ordinary rendition and many other actions undermining the open society. Once this happens, trust is living on borrowed time. That is very clearly the case in many developed societies today.

Trust in existing organizational structures does not disappear overnight, but ebbs away as institutions decay or the extent of their corruption is revealed. The loss of trust from higher levels of organization undermines the fabric of a society now operating beyond the trust horizon. When trust contracts, socioeconomic contraction is just around the corner. Bank runs are a particularly good example of this. People are currently waking up to the extent of the recklessness, irresponsibility and self-serving short-termism of the banking system, and realizing that reliance on top-down human promises is far riskier than they had supposed. When they cease to trust in those promises, they will are very likely to vote with their feet.

Societies in this position lose a critical pillar of support – the collective acceptance of their people. Governing institutions lose legitimacy, at which point the cost of governance increases significantly, because where there is no trust, resource-intensive surveillance and coercion develop instead. Our societies in the developed world, where institutional decay is well underway, stand on the brink of such a transition.

Where resources are scarce, as they will be soon enough, the diversion of a larger percentage of what remains towards this purpose will aggravate that scarcity considerably. This will further anger people, which is likely to lead to a downward spiral of mutual provocation and recrimination. Most of us have not seen this vicious circle of human sentiment to any great extent, but this is the natural consequence of the collapse of trust.

On the way down, as on the way up, there are effects both within and between societies, as the ‘Us vs Them’ dynamic sharpens once again. ‘Us’ becomes ever more tightly defined, and ‘Them’ becomes an ever more pejorative term. The result is division between disparate groups of people within a society, for instance the unionized and non-unionized, the haves and the have-nots, or different religious or ethnic groups. When there is a paucity of trust, and not enough resources to go meet highly inflated expectations, the risk of conflict is very high. Previously formed political accretions are at a high risk of coming unglued as they will no be longer supported by trust. The European Union should take note.

Between societies, where the existing range of divisive parameters is likely to be much larger, and where there may be a past history of conflict, the risk of conflict flaring up again rises significantly. This is especially likely if societies attempt to deflect blame for the situation they find themselves in towards other nationalities.

We are already seeing evidence of the growing anger, and the change it will usher in as the trust horizon shrinks. In the US, the Tea Party movement is the most obvious example. All major change comes from the ground-up, where the power of the collective is expressed in ways that either support or undermine the actions and intentions of central authorities. It is the interaction between the power of the collective and central authority that determines where a society will head.

The Tea Party movement is a ground-swell of public anger, very much in the tradition of major transformative grass-roots initiatives. It is exactly what one would expect to see at the brink of a collapse in the trust horizon – a movement grounded in negative emotion that both stems from a loss of trust and in turn acts to aggravate it in a self-reinforcing positive feedback loop. The danger with such a movement manifesting such powerful negative emotions is that it will precipitate a major over-reaction to the downside, commensurate with the irrational exuberance we saw to the upside. The anger is largely unfocused, and where it is specific, it is not fully-informed.

The primary target of the Tea Party is big government, but this ignores a major part of the big picture. The abuses of power we have seen are not purely a manifestation of metastatic public authority, but an expression of corporate fascism – the blending and merging of public and private interests in social control. One look at the revolving door between the banking system (where banking law is written) and the US treasury should be enough to demonstrate this.

The Tea Party movement represents largely (but not solely) the unfocused anger of people who know they have suffered, or are about to suffer, substantial losses, but do not (typically) understand the system well enough to understand why. The movement is casting about for someone to blame, as such movements always do on the verge of a trust collapse. The danger is that someone with facile populist answers will come along, offering a target for the urgent desire to blame someone for what has happened and is happening.

This is already happening, as powerful funding sources and nascent populists circle around and seek to tap into the trend for their own purposes. It is absolutely to be expected that existing top-down power structures, or political opportunists with their own agenda, will seek to hijack bottom-up movements as they develop. My primary concern is that in doing so they will lay the foundation for a society attempting to live far beyond the trust horizon, and where there is no trust, and consequently no political legitimacy, there will be surveillance, coercion and repression instead.

It will be easy for movements grounded in negative emotion to gain a foot-hold in the coming environment, as this is very much where the collective mood will lie in the aftermath of a Ponzi collapse. Blame-games will be very tempting (and populists have their own prejudicial ideas as to who should be blamed). However, this would not be compatible with maintaining the constructive and cooperative mindset we need if we are to have a hope of avoiding an over-reaction to the downside that has the potential to magnify the impact of what is coming enormously.

Personally, I would like to encourage the development of a different kind of grass-roots momentum for change, along the lines of what is being developed (albeit not nearly quickly enough so far) by the Transition Towns movement and other comparable initiatives. The key advantages that this kind of approach has are two-fold – the scope of its component activities, based on relocalization, match where the trust horizon is headed, and its driving force is the desire to build rather than to tear down.

Working within the trust horizon is important, as it means individual small-scale initiatives can benefit from the same kind of social support at a local level that larger-scale ones once did at a societal level, when trust was more broadly inclusive. Local currencies work for exactly this reason. While the task will still be difficult, it has a chance of being achievable, especially where the necessary relationships of trust have been established before hard times set in. It is very much more difficult to build such relationships after the fact, but relationships built beforehand may actually strengthen when put to the test.

Trying to maintain a positive and constructive focus at the local level, where trust has a chance to survive, and perhaps even thrive in hard times, and to avoid being drawn into a blame-game, will be an uphill battle. It is nevertheless something we need to do as a society, if we are to have a chance to preserve as much as possible of who we are through what is coming.

Posted in Advice | Comments Off on The need for trust